← Track record

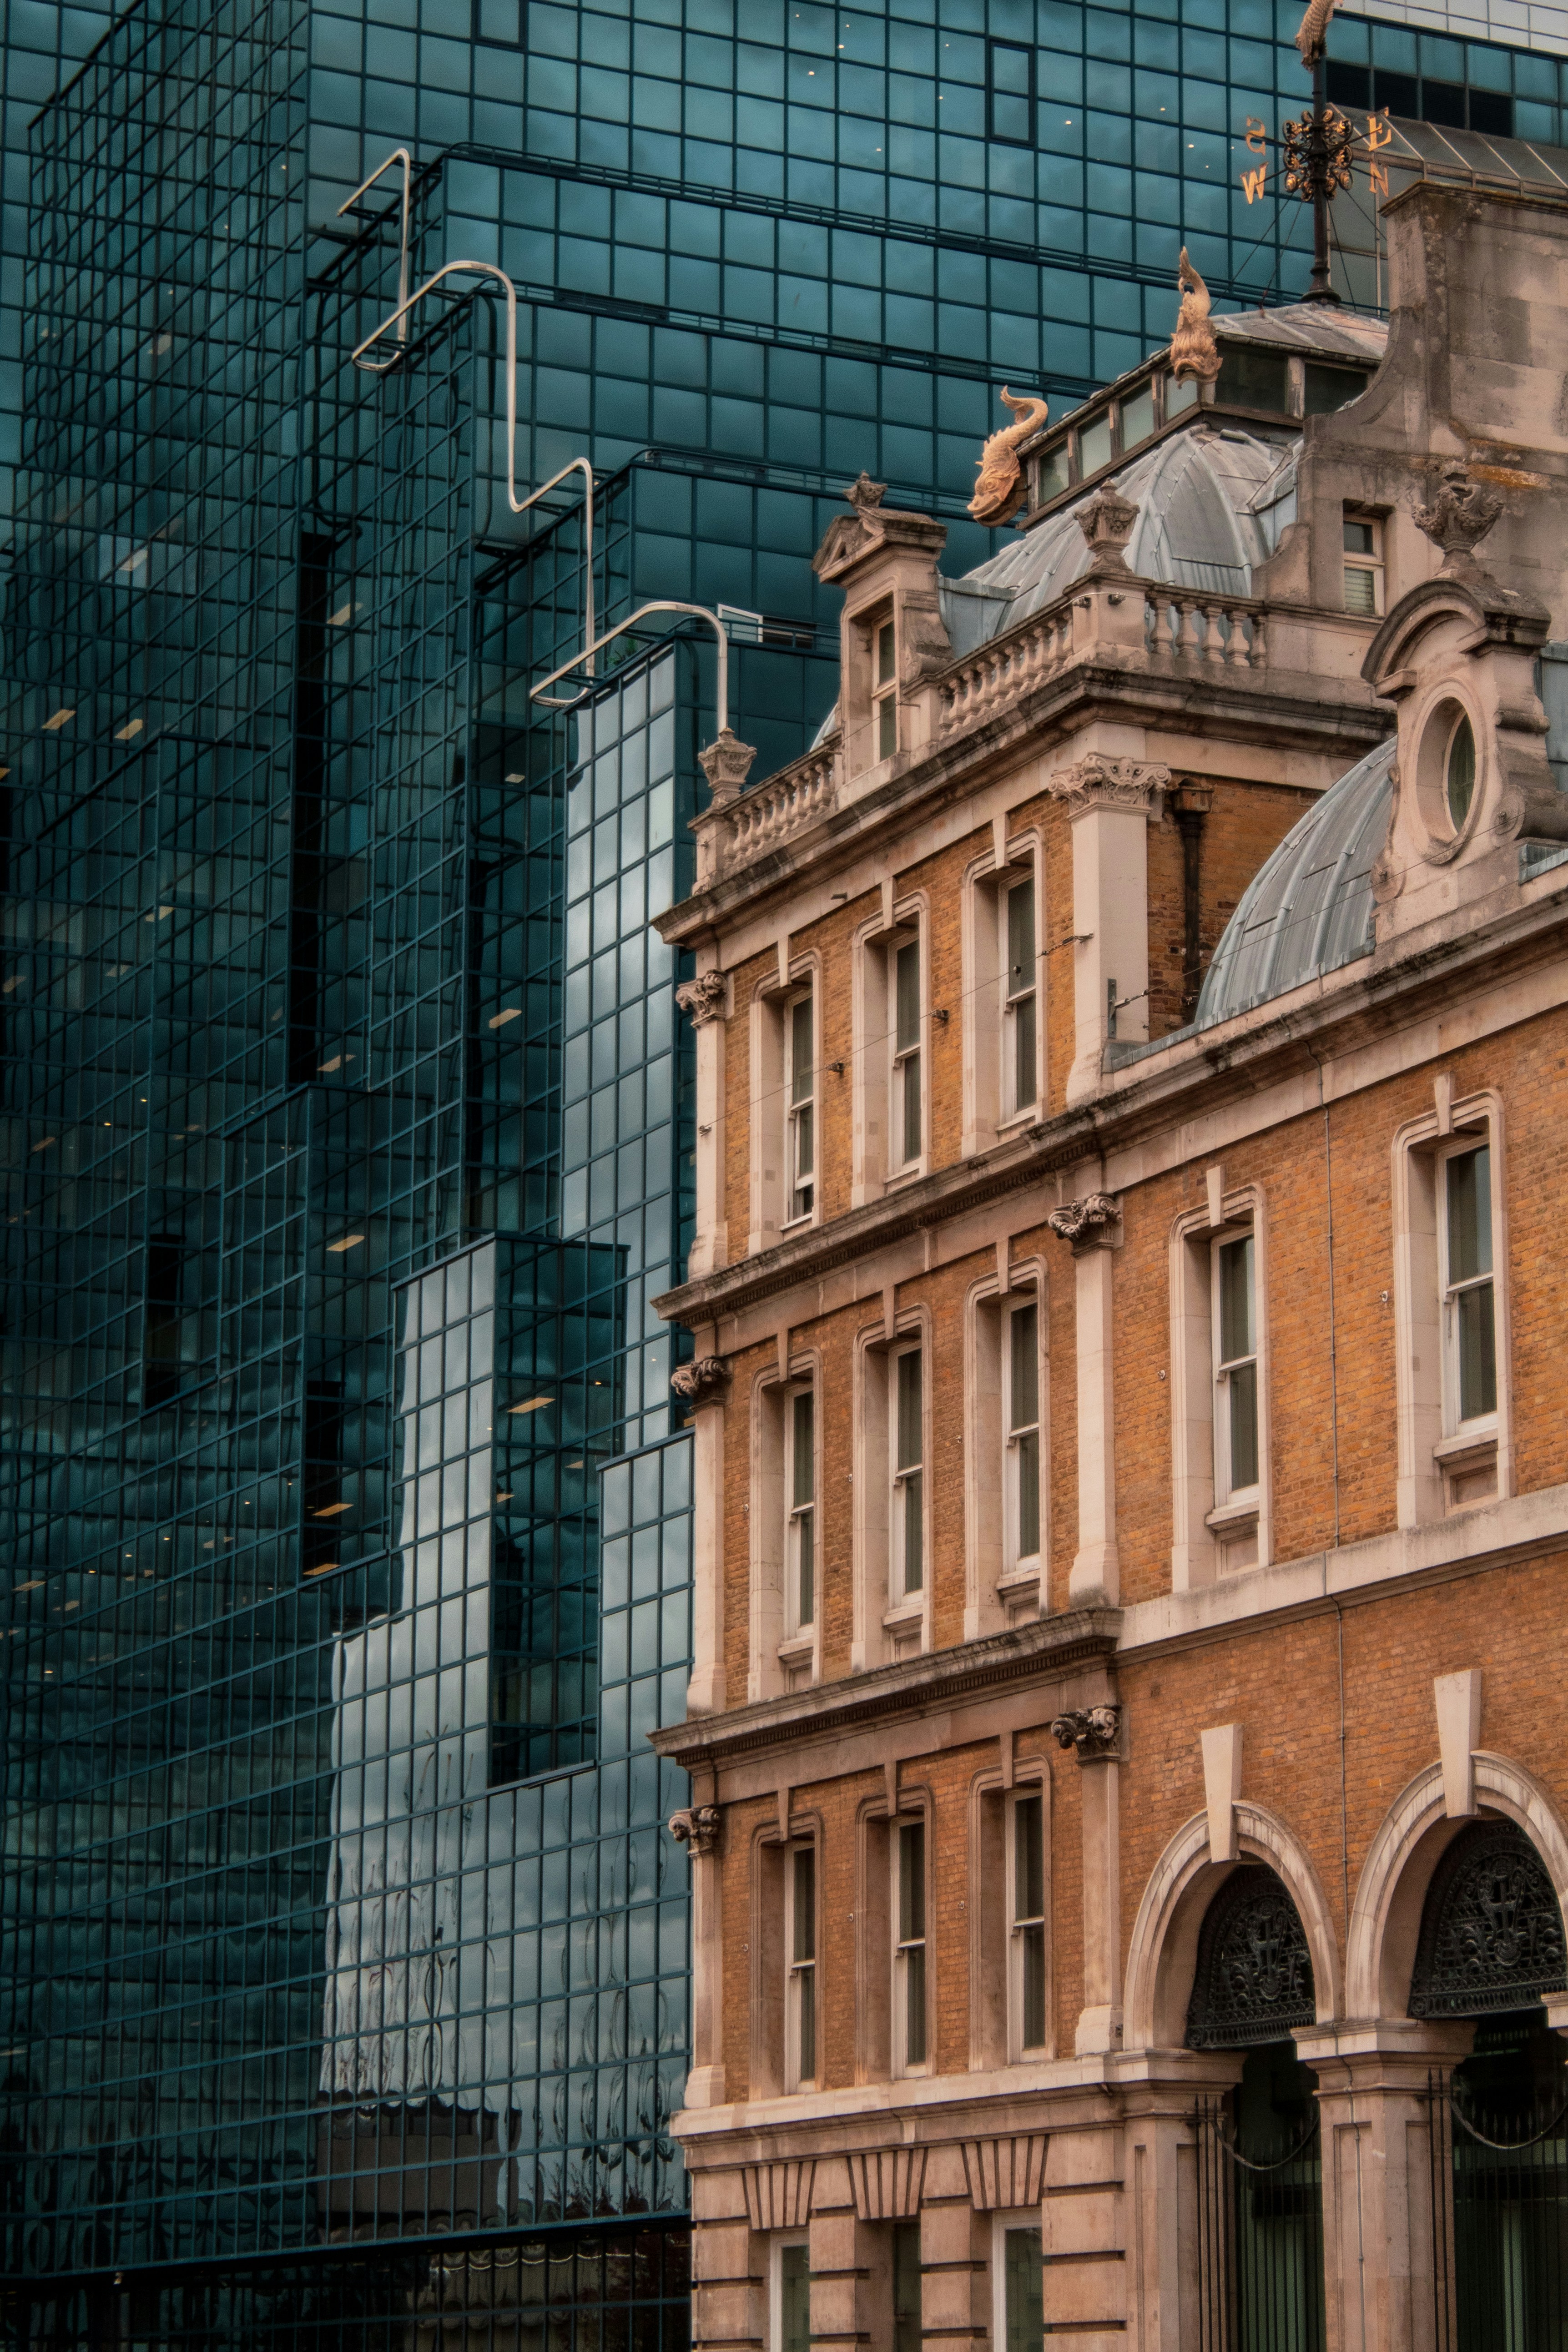
110 Golden Lane, London

Refurbishment and re-letting of six-floor office building

Sector

›

Developments

Location

›

London

Timeframe

›

2021
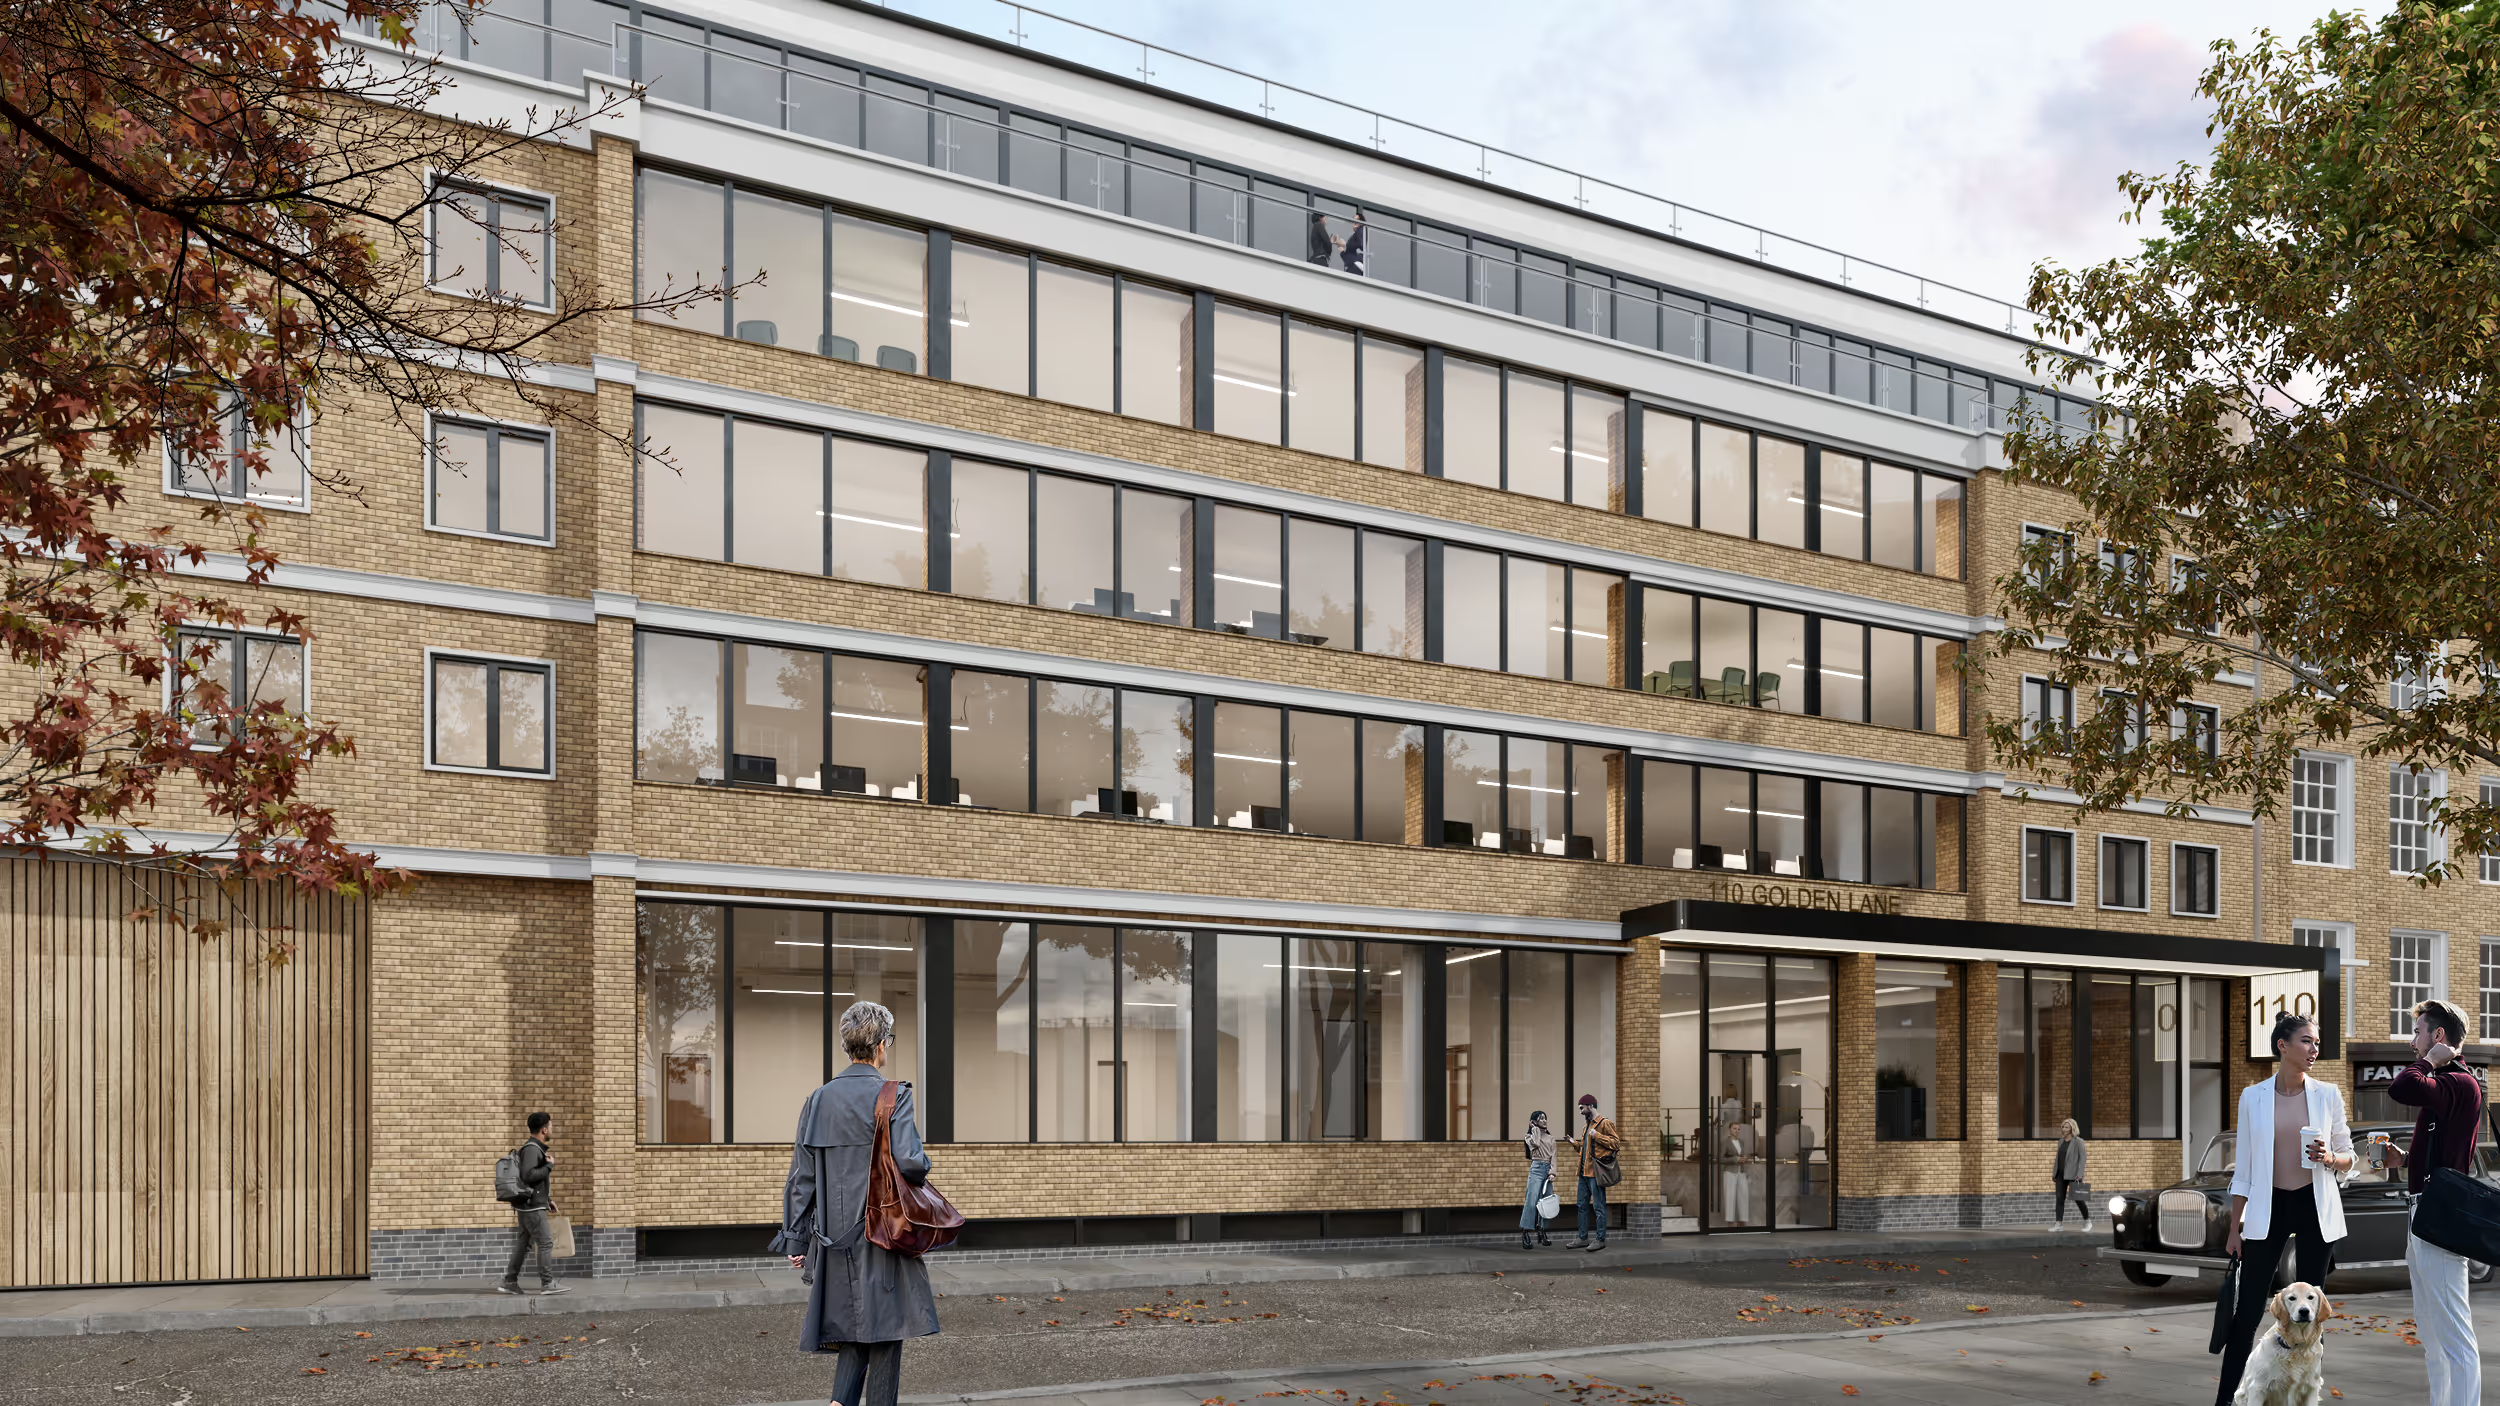
110 Golden Lane, London

In this record

The Opportunity

Long-term thinking helped Maritime revitalise an office building and create an outstanding value for money deal.

When 110 Golden Lane was acquired in 2021 the premises were only partially let, with short-term tenant leases due to expire imminently.  

Spread over six floors and only 50% let, the property needed some investment if it was to attract the calibre of tenant to ensure it thrives and produces a good return.

Our Approach

We approached this as a value for money project and set about negotiating longer leases with current tenants in exchange for lower terms, ultimately reducing void times. 

Other property professionals would have taken a different approach to 110 Golden Lane, opting for expensive Category-A+ fit-outs and attracting short-term tenants with rent-free periods.

This method looks good on paper, but leads to longer void times and reduced income due to a potential ‘revolving door’ of tenants.

Maritime are investing £750,000 in refurbishing the building, spending money prudently on the reception and common areas, as well as modernising the exterior to visually tie together all aspects of the building and create an attractive office proposition.

The Result

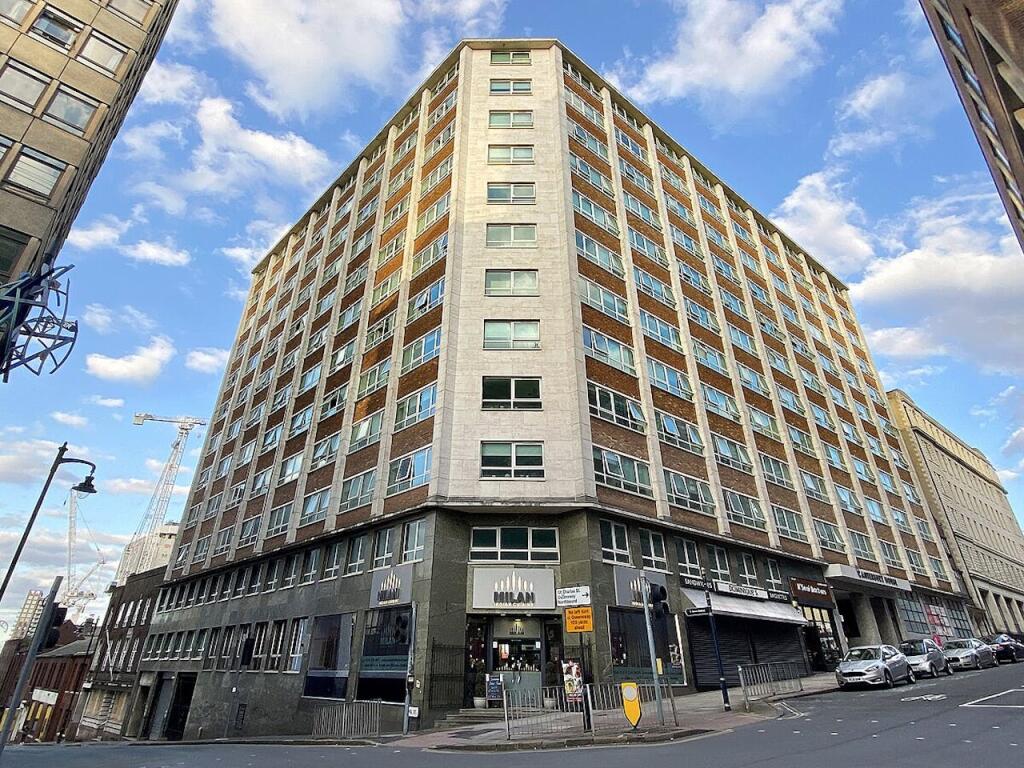
Today 110 Golden Lane is very different asset to the one we took on. The building is now fully let, with new tenants taking straight 10-year leases attracted by reduced rents and existing occupants expanding their footprint.

This approach ultimately gives us a better return due to reduced void times, with the asset producing £879kpa and RPI increases in the pipeline.
‍

Speak to our team

An office sitting half-empty?

We took 110 Golden Lane from half-let to fully let by trading headline rent for long, secure leases and far shorter voids. Sometimes the better return comes from the patient option, not the obvious one.

Continue reading

Key insights

Wealth & Family Office

Why family offices invest in real estate

Real estate sits alongside equities, private equity and fixed income in most family office portfolios – but it behaves differently to all of them, and that's exactly why it earns its place.

5

Real estate is one of the core asset classes in most family office portfolios, alongside public equities, private equity, fixed income and increasingly private credit. Family office asset allocation to real estate has grown in recent years, driven by its long-term yield, its role as a diversifier against public markets, and its suitability for multi-generational holding periods that few other asset classes match.

Where real estate fits in family office asset allocation

Family offices typically hold a mix of private equity and direct investments, real estate, public equities, fixed income and alternative investments, with the exact split varying by size, generational stage and risk appetite. Real estate tends to justify its place in that mix for reasons other asset classes don't share: a steady, long-term income yield; a long holding horizon that matches how families think about multi-generational wealth; and enough direct control that a family can shape an asset's performance rather than simply hold a position and wait.

How family offices access real estate

Once real estate earns its place in the allocation, there's a separate question of how to access it – directly, or through a fund or REIT structure. That decision affects fees, control and liquidity in more depth than an allocation discussion needs to cover; the trade-offs are set out in full in our guide to financial planning for property investment. What matters at the allocation level is simpler: direct ownership is what lets a family actively shape a property's performance rather than passively hold a position in it, which is a large part of why real estate earns a place in the portfolio in the first place.

Discovery Park in Kent is a clear illustration of what that control can achieve. Brought under active management, the science park's capital value grew from around £20m to more than £75m over two years – restructuring leases and separating out service charges rather than simply holding the asset and waiting. A passive fund position, with no say over how the asset is run, couldn't have delivered the same outcome.

What family offices are actually buying

UK real estate remains a core allocation, but the mix within it is shifting. Portfolios are diversifying into student accommodation, retail parks and leisure assets alongside the more traditional office and residential holdings, and branded hotel and hospitality assets remain in favour where they carry a strong covenant. Family offices weighing new allocations are also factoring in wider considerations earlier than before – joint venture and asset management arrangements, transparency requirements such as the Land Registry's Persons of Significant Control and Overseas Entities registers, and planning and tax implications specific to the deal.

Maritime Capital's own track record reflects the same pattern of diversification: self-storage and leisure conversions such as Storage Box in Hersham, branded hospitality including The Forbury Hotel in Reading and Raithwaite Sandsend in Yorkshire, and retail assets alongside the more familiar office and residential holdings. The common thread isn't the sector – it's a covenant and a business model resilient enough to justify the allocation in the first place.

Why real estate suits multi-generational wealth

Few asset classes hold up as well across multiple generations as real estate. A well-managed property can be improved, repositioned and passed down without a fixed exit forced by a fund's term, which matters to families thinking in decades rather than years. That said, realising the benefit depends on active management – a passively held property doesn't generate the same value as one where lease strategy, service charge control and repositioning decisions are being made deliberately.

Hungerford Park shows what that looks like over a genuinely long horizon. Acquired in 2005 as a 300-acre estate, it's been built over two decades into a working farm, a holiday-let business and an events venue – the kind of layered, multi-generational value creation that a fund's fixed term could never accommodate, and that only comes from treating the asset as a long-term project rather than a static holding.

Getting the right support

Most family offices don't carry deep in-house real estate expertise alongside their wider investment team, which is why property is often the asset class most commonly brought in through a specialist partner rather than managed entirely in-house. Maritime Capital works alongside family offices and their existing advisers – wealth managers, investment managers and private banks – on the UK commercial property portion of the portfolio specifically, from acquisition through to ongoing asset and property management.

‍

Commercial Property

Complex property restructuring

When a property holding structure starts to work against the assets it was built to protect, clear action matters.

8

At this level, the issue rarely sits in one place. Debt terms, ownership structures, tax position, tenant strength, development cost, lender expectations and family governance are often linked. Real estate restructuring therefore calls for a joined-up review of the assets, the liabilities and the people around them.

What complex property restructuring actually means

Complex property restructuring is the strategic, legal and financial reorganisation of real estate assets, portfolios or holding structures.

The objective is to protect value, improve performance, manage risk and create practical solutions when a portfolio is under pressure or preparing for a major transaction.

It can involve:

  • Reshaping the capital structure of a property company or wider group
  • Separating strong assets from weaker ones
  • Addressing debt maturities, covenant pressure and non-performing loans
  • Resolving tenant default, rent collection issues or occupancy weakness
  • Redesigning operational and asset management plans
  • Reorganising ownership between companies, trusts, SPVs, joint ventures or family entities
  • Preparing distressed assets or development projects for refinancing, turnaround or disposal

lIn larger portfolios, the best outcome often comes from combining corporate restructuring, financial restructuring and operational turnaround rather than treating each issue in isolation.

When real estate restructuring becomes necessary

Property owners rarely reach this point because of one single event. More often, several market challenges arrive at once. Common triggers include:

  • Upcoming refinancing deadlines with no straightforward route to replacement debt
  • Lenders or banks pressing for deleveraging, disposals or additional security
  • Underperforming retail, hospitality or mixed-use assets
  • Stalled development projects where cost inflation, delays or weaker demand have changed the original business plan
  • Residential properties held in outdated structures that no longer suit the family’s wider objectives
  • Tenant default, arrears or lease expiry concentrations
  • Fragmented ownership that makes decision-making slow or contested
  • Distress within a borrowing entity, a guarantor or a related business
  • A planned sale where the existing structure would reduce value or deter investors

For sophisticated investors, restructuring is often about timing. Early action tends to preserve more available options. Late action usually narrows them.

The first questions to assess

Before any restructuring plan is discussed, a portfolio needs a hard-headed review. That means looking past headline valuations and asking what is actually driving performance, pressure and risk. A proper assessment should cover:

  • The ownership chain and who controls each asset
  • Secured debt, mezzanine debt, guarantees and contingent liabilities
  • Loan maturities, covenant tests, interest cost and cash sweep provisions
  • Lease profile, rent roll, arrears and exposure to tenant concentration
  • Capex requirements, planning position and development viability
  • Tax consequences in relation to transfers, refinancings, disposals and new capital
  • Cross-defaults between companies, facilities and related entities
  • The quality of data available to lenders, investors and advisers
  • The realistic time available before creditor action becomes a problem

This is usually where chartered surveyors, legal advisers, tax specialists and insolvency practitioners begin to work alongside asset management and restructuring specialists. Independent valuation standards matter because lenders, investors and boards need decisions to be based on defensible evidence, not optimism.

What the restructuring process usually involves

There is no single template for complex property restructuring, but the process tends to move through the same core stages.

  1. Establish the real position. The first task is to assess the portfolio properly. That includes updated valuations, cash flow forecasting, debt mapping, lease analysis and a realistic view of each asset’s marketability. If the information is weak, the process slows and leverage shifts towards lenders and other stakeholders.
  2. Separate strategy from sentiment. Families and founders often have long histories with specific buildings, sectors or regions. That perspective matters, but restructuring decisions still need to be based on current value, future viability and cost of capital. Some assets should be protected and refinanced. Some need intensive asset management. Some are better sold.
  3. Define the available options. The available options may include:
    • Consensual negotiations with lenders and creditors
    • Amendments to repayment profiles or covenant packages
    • Fresh equity or preferred capital
    • Refinancing with alternative lenders, debt funds or private capital
    • Sales of selected assets or non-core portfolios
    • Changes to the corporate or trust structure
    • Formal insolvency or court-led tools where private agreement cannot be achieved
  4. Choose the right route for each asset and entity. A portfolio does not have to move in one direction. One company may need administration protection, another may be suitable for a restructuring plan, while a third may only require lighter-touch refinancing and tighter operational controls.
  5. Execute with discipline. Once the route is chosen, execution becomes critical. Documents, valuations, stakeholder communications, board decisions and reporting all need to align. Directors also need to be clear about their duties if insolvency risk is present.

The main tools used in complex property restructuring

The right tools depend on the level of distress, the quality of the assets and the willingness of stakeholders to negotiate.

Consensual negotiations

For many portfolios, the best starting point is private, commercial negotiations. Borrowers, lenders and investors may be able to agree waivers, standstill arrangements, covenant resets, revised amortisation or partial disposals without a formal insolvency process. This route can preserve value, reduce cost and maintain confidentiality. It also depends on credibility. Lenders respond better when borrowers provide clean information, realistic forecasts and a workable plan.

Refinancing and capital restructuring

Where the asset base is sound but the debt is wrong, financial restructuring can focus on the capital structure itself. That may mean replacing short-term debt, bringing in new capital, extending maturities, selling non-performing loans or rebalancing the mix between senior debt, mezzanine finance and equity. For high-value portfolios, refinancing is often linked to wider questions of ownership, tax efficiency and future exit plans. The cheapest capital is not always the best capital if it restricts control or narrows future options.

Corporate restructuring

A corporate restructuring may involve simplifying SPVs, separating operational businesses from property ownership, revising shareholder arrangements, resolving JV misalignment or reorganising group liabilities. For real estate companies with multiple assets, this can make the difference between an orderly solution and a drawn-out value leak. Done well, corporate restructuring can:

  • Ringfence risk
  • Improve reporting and governance
  • Make refinancing more achievable
  • Simplify a sale
  • Give investors and lenders clearer security and cleaner decision-making

Formal restructuring and insolvency tools

Where negotiations cannot resolve the pressure, formal tools may need to be considered. In the UK, that can include a moratorium, administration, a company voluntary arrangement in the right circumstances or a court-approved restructuring plan for companies facing financial difficulty. These are specialist processes. They can be powerful, but they need careful handling. Formal insolvency should not be viewed as a loss of control in every case. Sometimes it is the route that protects the most value, preserves the strongest assets and creates the clearest outcome for creditors and owners.

Distressed assets need more than debt advice

Distressed assets are often discussed as though the answer sits entirely with the lenders. In practice, many real estate problems are partly operational. A building may suffer because the tenant mix is wrong, service charge recovery is poor, capital expenditure has been delayed, planning potential is ignored or the rent strategy no longer fits the market. In development projects, the issue may be procurement, phasing, funding drawdowns or exit timing. That's why real estate restructuring often overlaps with asset management and turnaround work such as:

  • Reletting or re-gearing leases
  • Reworking tenant strategy in retail and hospitality assets
  • Controlling arrears and managing landlord and tenant disputes
  • Revising development appraisals and delivery plans
  • Securing planning improvements or alternative use value
  • Disposing of weaker assets to protect the wider portfolio
  • Preparing a clean investment case for new funds or incoming investors

A strong restructuring process should improve the asset, not simply rearrange the debt.

Legal, tax and governance issues that deserve early attention

For substantial portfolios, the detail matters just as much as the headline strategy. Particular points to evaluate early include:

  • Directors’ duties if a company is insolvent or likely to become insolvent
  • Guarantees, security packages and cross-collateralisation
  • Transfers at undervalue or preferential treatment of connected parties
  • Tax leakage arising from asset transfers, debt releases or changes in ownership
  • Lender consent rights and intercreditor arrangements
  • Beneficial ownership, governance and control across family structures
  • Reporting obligations where international clients hold UK assets through layered entities
  • Reputational management in relation to tenants, lenders and counterparties

Late action usually reduces room for manoeuvre. Early action gives borrowers more time for negotiations, a better chance of consensual solutions and more influence over the final plan.

Preparing a portfolio for sale through restructuring

Sometimes the purpose of restructuring is not long-term retention, it's to facilitate a sale. In those cases, the focus shifts to making the assets easier to understand, finance and underwrite. Buyers and their lenders want clean title, coherent ownership, reliable data, realistic valuations and evidence that major liabilities are understood. Sale preparation may involve:

  • Simplifying ownership structures
  • Settling disputes or contingent claims
  • Cleaning up intra-group balances
  • Resolving planning or occupational issues
  • Disposing of peripheral assets
  • Separating core income-producing assets from operational businesses
  • Producing a clearer narrative around future value creation

This can materially improve pricing and widen the pool of potential buyers.

How sophisticated investors manage risk during restructuring

Experienced investors tend to approach restructuring in a disciplined way. They do not wait for a maturity date or a default notice before they act. They monitor leading indicators, pressure test funding assumptions and stay close to the detail. A sensible framework usually includes:

  • Regular portfolio reviews at asset and entity level
  • Downside cash flow modelling
  • Early engagement with lenders and key stakeholders
  • Independent valuation and market testing
  • Clear delegation and governance
  • Specialist advice across legal, tax, finance and asset management disciplines
  • A defined view on what must be protected, what can be sold and what needs turnaround work

For families with large portfolios, that discipline also helps maintain continuity across generations and advisers.

Wealth & Family Office

Financial planning for property investment

Financial planning for property investment at a serious level starts long before an acquisition.

5

For high-net-worth property investors, property investment needs to sit within a wider wealth plan, with clear expectations around cash flow, control and long-term capital growth.

For families allocating substantial capital, commercial property calls for a broad view.

The right investment should strengthen a wider property portfolio, sit sensibly alongside other asset classes and reflect your long-term investment goals, risk appetite and overall financial health.

Start with strategy

A strong property investment strategy begins with a simple question. What should property do for you? For some families, the priority is consistent rental income.

For others, it is capital appreciation and equity growth over time.In most cases, it is a blend of both, shaped by personal circumstances and the role UK property plays within the wider family balance sheet.

This is why financial planning for property investment cannot be separated from financial health. If you start investing without clarity on liquidity, succession, tax exposure and governance, the asset can start to drive the plan.

Good property investing should spread risk across tenants, locations and property types. It should fit your wider investment strategy.

For Maritime Capital's family of clients, that often points towards commercial property across retail, industrial and other income-producing sectors rather than a collection of smaller domestic assets.

A carefully selected investment property with the right tenant mix and asset management plan can offer more control over value creation than a passive approach to investing in property.

Focus on cash flow

Strong rental income matters, but headline rent is only the starting point. Sophisticated property investors look at rental yield, net yield and cash flow after mortgage repayments, mortgage interest, insurance, incentives, void periods, maintenance and all the costs that sit between gross income and spendable returns.

Unexpected repairs and hidden costs have a habit of arriving at the worst moment and can quickly weaken a poorly planned deal. That's why every acquisition deserves a proper stress test. If interest rates remain higher than expected, if mortgage rates move, or if a tenant leaves, does the asset still produce consistent rental income?

In commercial property, a well-structured lease can support resilience, but no one should assume the property market will carry the full weight on its own.

Property management also has a direct bearing on returns. Weak property management can dilute rental income, drag on market value and reduce the capital growth you hoped to achieve. Strong property management protects tenant relationships, maintains standards and helps sustain property values over time.

Get the structure right from day one

Ownership structure shapes returns just as much as location or tenant quality. The tax treatment of a property held personally can look very different from one held through a limited company or another family structure.

Income tax, capital gains tax, stamp duty and wider tax implications should be reviewed early, while there is still time to plan properly.For larger acquisitions, stamp duty land tax costs need to be built into pricing from the outset.

So do the likely tax implications of future capital gains, any plan to release equity from a mature asset and the impact of leverage on long-term capital growth.

Your financial adviser, tax adviser and legal team should be aligned before exchange, so the investment decision works on paper and in practice.

This is also where specialist advice earns its place. The right property experts will test legal structure, financing, exit routes and debt strategy together.

Expert advice should focus on how a deal performs over time, especially when conditions change.

Be selective about sectors and access routes

Not every investment opportunity deserves capital. Due diligence should test the tenant covenant, lease terms, refurbishment exposure, environmental issues, planning constraints, local competition and the relationship between purchase price, market value and replacement risk.

In a changing property market, trends matter, but they should inform judgment rather than override it.

Prime offices and well-located industrial assets can still benefit from tight supply in many areas, while retail recovery remains selective and secondary stock needs far more caution.

For high-net-worth families, the strongest opportunities are often found where deep due diligence and active asset management can improve performance.Some investors use property funds or real estate investment trusts to gain exposure to the sector.

That can be useful for liquidity and diversification, but it also creates distance from the underlying asset and the property investment strategy attached to it.

Families who want direct control over leasing, financing, development and exit timing often prefer direct ownership to passive property funds. The choice depends on your investment goals, your risk tolerance and how hands-on you want to be.

Build the exit strategy before you commit

Every serious property investment strategy needs a clear exit strategy before the acquisition closes.

Are you buying for income, repositioning for sale, holding for capital appreciation, or planning to refinance and release equity for the next investment opportunity?

That answer influences financing, tax, asset management and the pace at which capital gains may be realised.

The right investment is rarely the most obvious asset on the market. It is the one that fits your wider wealth plan, strengthens your property portfolio and gives you room to buy property with confidence when conditions change.

‍

Plan with clarity and purpose

Maritime Capital work alongside family offices, private clients and their advisers to shape considered commercial property strategies in the UK.

We work with clients with portfolios of £50m or more who want property to serve a defined role within long-term family wealth.

From acquisition and due diligence to property management and exit planning, our focus is on helping you make informed decisions that protect capital and create real, measurable value.

110 Golden Lane, London

Long-term thinking helped Maritime revitalise an office building and create an outstanding value for money deal.

When 110 Golden Lane was acquired in 2021 the premises were only partially let, with short-term tenant leases due to expire imminently.  

Spread over six floors and only 50% let, the property needed some investment if it was to attract the calibre of tenant to ensure it thrives and produces a good return.

We approached this as a value for money project and set about negotiating longer leases with current tenants in exchange for lower terms, ultimately reducing void times. 

Other property professionals would have taken a different approach to 110 Golden Lane, opting for expensive Category-A+ fit-outs and attracting short-term tenants with rent-free periods.

This method looks good on paper, but leads to longer void times and reduced income due to a potential ‘revolving door’ of tenants.

Maritime are investing £750,000 in refurbishing the building, spending money prudently on the reception and common areas, as well as modernising the exterior to visually tie together all aspects of the building and create an attractive office proposition.

Today 110 Golden Lane is very different asset to the one we took on. The building is now fully let, with new tenants taking straight 10-year leases attracted by reduced rents and existing occupants expanding their footprint.

This approach ultimately gives us a better return due to reduced void times, with the asset producing £879kpa and RPI increases in the pipeline.
‍

wealth guardian brochure

DOWNLOAD