Redevelopment of retail parade for residential and retail scheme
Sector
›
Retail
Location
›
Newbury, Berkshire

In this record
Our aptitude for recognising unseen potential and secondary value is exemplified by this project in Newbury, Berkshire.
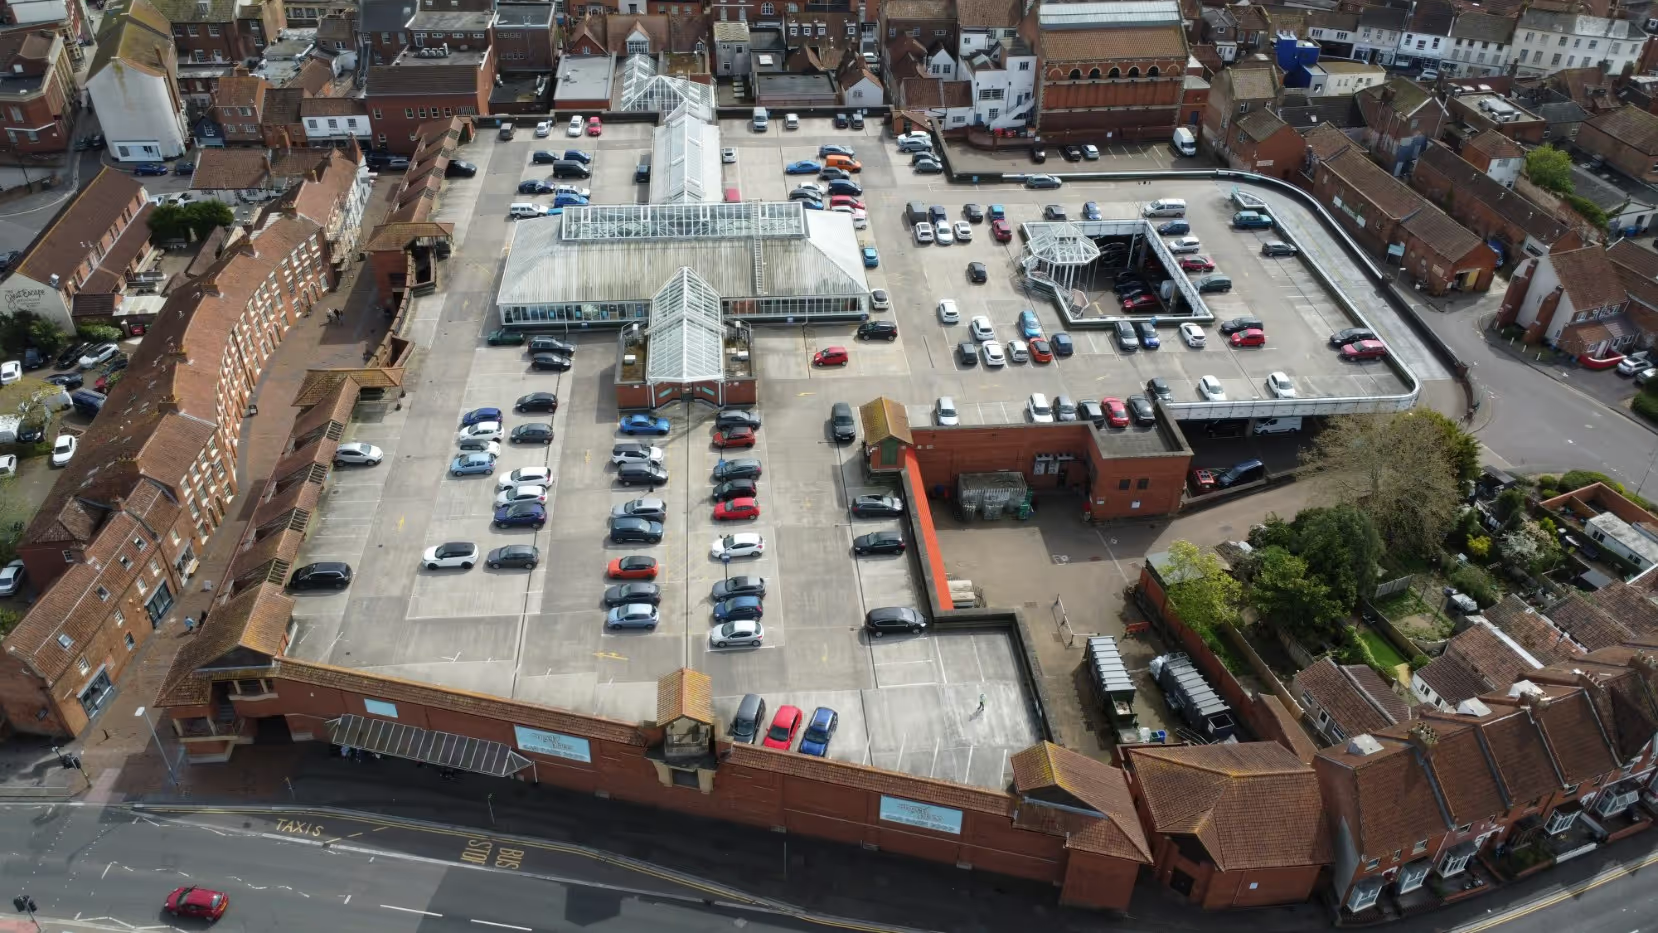
Given the large service yard and car park that came with this high street retail shop, we could immediately see a development opportunity..
Situated in central Newbury the retail parade, with Iceland as its anchor tenant, was burdened with an unsightly 1960s office block on the first floor.
In order to stabilise income from the retail unit and create more frontage for another retail unit, we made the decision to demolish the offices above.
This removed the empty rates, and allowed us to create 15 more car parking spaces to the rear.
The removal of the ground floor office entrance allowed us to create another valuable shop unit and we were then able to renegotiate a lease with Iceland, taking into account the increased number of parking spaces to the rear, creating a much stronger investment.
The previous owners had only seen a complicated, empty 1960s office building with car parking for the office building and the Iceland store.
What they had missed was the opportunity to remove the offices and build over the whole site, creating the conditions for a potential residential scheme.
We obtained planning permission for a new scheme containing 25,000 sq ft of residential and 15,000 sq ft of retail, allowing us to sell the site with a massive premium on its purchase price, due to its increased value to developers.
A major residential scheme has now been implemented on the site.
Speak to our team
By removing an unloved office block and securing planning for homes and retail, we sold Bartholomew Street at a substantial premium. Secondary value is often there for those willing to look.
Continue reading
Key insights
Real estate sits alongside equities, private equity and fixed income in most family office portfolios – but it behaves differently to all of them, and that's exactly why it earns its place.
Real estate is one of the core asset classes in most family office portfolios, alongside public equities, private equity, fixed income and increasingly private credit. Family office asset allocation to real estate has grown in recent years, driven by its long-term yield, its role as a diversifier against public markets, and its suitability for multi-generational holding periods that few other asset classes match.
Family offices typically hold a mix of private equity and direct investments, real estate, public equities, fixed income and alternative investments, with the exact split varying by size, generational stage and risk appetite. Real estate tends to justify its place in that mix for reasons other asset classes don't share: a steady, long-term income yield; a long holding horizon that matches how families think about multi-generational wealth; and enough direct control that a family can shape an asset's performance rather than simply hold a position and wait.
Once real estate earns its place in the allocation, there's a separate question of how to access it – directly, or through a fund or REIT structure. That decision affects fees, control and liquidity in more depth than an allocation discussion needs to cover; the trade-offs are set out in full in our guide to financial planning for property investment. What matters at the allocation level is simpler: direct ownership is what lets a family actively shape a property's performance rather than passively hold a position in it, which is a large part of why real estate earns a place in the portfolio in the first place.
Discovery Park in Kent is a clear illustration of what that control can achieve. Brought under active management, the science park's capital value grew from around £20m to more than £75m over two years – restructuring leases and separating out service charges rather than simply holding the asset and waiting. A passive fund position, with no say over how the asset is run, couldn't have delivered the same outcome.
UK real estate remains a core allocation, but the mix within it is shifting. Portfolios are diversifying into student accommodation, retail parks and leisure assets alongside the more traditional office and residential holdings, and branded hotel and hospitality assets remain in favour where they carry a strong covenant. Family offices weighing new allocations are also factoring in wider considerations earlier than before – joint venture and asset management arrangements, transparency requirements such as the Land Registry's Persons of Significant Control and Overseas Entities registers, and planning and tax implications specific to the deal.
Maritime Capital's own track record reflects the same pattern of diversification: self-storage and leisure conversions such as Storage Box in Hersham, branded hospitality including The Forbury Hotel in Reading and Raithwaite Sandsend in Yorkshire, and retail assets alongside the more familiar office and residential holdings. The common thread isn't the sector – it's a covenant and a business model resilient enough to justify the allocation in the first place.
Few asset classes hold up as well across multiple generations as real estate. A well-managed property can be improved, repositioned and passed down without a fixed exit forced by a fund's term, which matters to families thinking in decades rather than years. That said, realising the benefit depends on active management – a passively held property doesn't generate the same value as one where lease strategy, service charge control and repositioning decisions are being made deliberately.
Hungerford Park shows what that looks like over a genuinely long horizon. Acquired in 2005 as a 300-acre estate, it's been built over two decades into a working farm, a holiday-let business and an events venue – the kind of layered, multi-generational value creation that a fund's fixed term could never accommodate, and that only comes from treating the asset as a long-term project rather than a static holding.
Most family offices don't carry deep in-house real estate expertise alongside their wider investment team, which is why property is often the asset class most commonly brought in through a specialist partner rather than managed entirely in-house. Maritime Capital works alongside family offices and their existing advisers – wealth managers, investment managers and private banks – on the UK commercial property portion of the portfolio specifically, from acquisition through to ongoing asset and property management.
Our aptitude for recognising unseen potential and secondary value is exemplified by this project in Newbury, Berkshire.
Given the large service yard and car park that came with this high street retail shop, we could immediately see a development opportunity..
Situated in central Newbury the retail parade, with Iceland as its anchor tenant, was burdened with an unsightly 1960s office block on the first floor.
In order to stabilise income from the retail unit and create more frontage for another retail unit, we made the decision to demolish the offices above.
This removed the empty rates, and allowed us to create 15 more car parking spaces to the rear.
The removal of the ground floor office entrance allowed us to create another valuable shop unit and we were then able to renegotiate a lease with Iceland, taking into account the increased number of parking spaces to the rear, creating a much stronger investment.
The previous owners had only seen a complicated, empty 1960s office building with car parking for the office building and the Iceland store.
What they had missed was the opportunity to remove the offices and build over the whole site, creating the conditions for a potential residential scheme.
We obtained planning permission for a new scheme containing 25,000 sq ft of residential and 15,000 sq ft of retail, allowing us to sell the site with a massive premium on its purchase price, due to its increased value to developers.
A major residential scheme has now been implemented on the site.