Debt-funded acquisition returning 16% a year on equity from rent alone
Sector
›
Industrial
Deal type
›
Acquisition
Value
›
£1.75m
Location
›
Falmouth, Cornwall
Timeframe
›
2007

In this record
The vendor, a large quoted company, had completed a well-publicised growth phase through acquisition and needed to dispose of liabilities from its accounts.
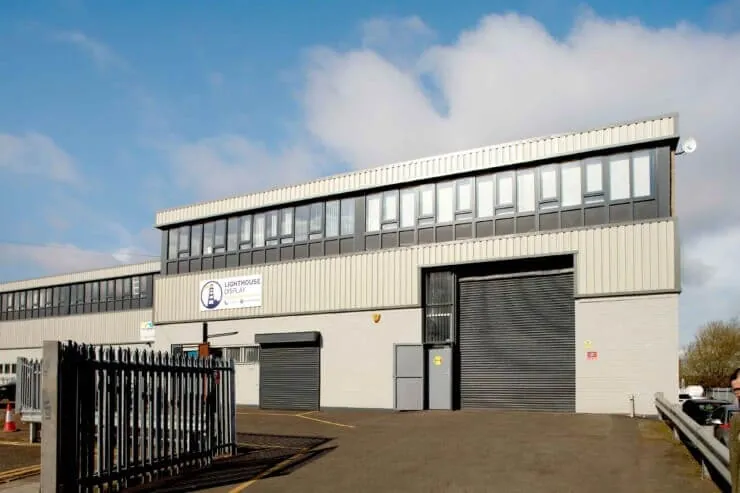
That gave us the chance to buy below value. The site was valued at £1.925m, and the low base rents and low capital value of the new building gave us confidence in the potential for both rental and capital growth.
In January 2007 we paid £1.75m for the site, or £1.835m including transaction costs. We funded it with £1.54m of debt at 5.5%, so debt servicing came to £85,000 a year against annual income of £132,000.
That left equity of £295,000, just 17% of the purchase price.
The investment produced a positive cashflow of £47,000 a year, an annual return of 16% on the capital invested from rent alone, with rental and capital growth still to come.
Speak to our team
A clear view of value, debt and income is what separates a good deal from an expensive one. For a considered second opinion, we would welcome a conversation.
United Arab Emirates
Singapore
Continue reading
Key insights
Real estate sits alongside equities, private equity and fixed income in most family office portfolios – but it behaves differently to all of them, and that's exactly why it earns its place.
Real estate is one of the core asset classes in most family office portfolios, alongside public equities, private equity, fixed income and increasingly private credit. Family office asset allocation to real estate has grown in recent years, driven by its long-term yield, its role as a diversifier against public markets, and its suitability for multi-generational holding periods that few other asset classes match.
Family offices typically hold a mix of private equity and direct investments, real estate, public equities, fixed income and alternative investments, with the exact split varying by size, generational stage and risk appetite. Real estate tends to justify its place in that mix for reasons other asset classes don't share: a steady, long-term income yield; a long holding horizon that matches how families think about multi-generational wealth; and enough direct control that a family can shape an asset's performance rather than simply hold a position and wait.
Once real estate earns its place in the allocation, there's a separate question of how to access it – directly, or through a fund or REIT structure. That decision affects fees, control and liquidity in more depth than an allocation discussion needs to cover; the trade-offs are set out in full in our guide to financial planning for property investment. What matters at the allocation level is simpler: direct ownership is what lets a family actively shape a property's performance rather than passively hold a position in it, which is a large part of why real estate earns a place in the portfolio in the first place.
Discovery Park in Kent is a clear illustration of what that control can achieve. Brought under active management, the science park's capital value grew from around £20m to more than £75m over two years – restructuring leases and separating out service charges rather than simply holding the asset and waiting. A passive fund position, with no say over how the asset is run, couldn't have delivered the same outcome.
UK real estate remains a core allocation, but the mix within it is shifting. Portfolios are diversifying into student accommodation, retail parks and leisure assets alongside the more traditional office and residential holdings, and branded hotel and hospitality assets remain in favour where they carry a strong covenant. Family offices weighing new allocations are also factoring in wider considerations earlier than before – joint venture and asset management arrangements, transparency requirements such as the Land Registry's Persons of Significant Control and Overseas Entities registers, and planning and tax implications specific to the deal.
Maritime Capital's own track record reflects the same pattern of diversification: self-storage and leisure conversions such as Storage Box in Hersham, branded hospitality including The Forbury Hotel in Reading and Raithwaite Sandsend in Yorkshire, and retail assets alongside the more familiar office and residential holdings. The common thread isn't the sector – it's a covenant and a business model resilient enough to justify the allocation in the first place.
Few asset classes hold up as well across multiple generations as real estate. A well-managed property can be improved, repositioned and passed down without a fixed exit forced by a fund's term, which matters to families thinking in decades rather than years. That said, realising the benefit depends on active management – a passively held property doesn't generate the same value as one where lease strategy, service charge control and repositioning decisions are being made deliberately.
Hungerford Park shows what that looks like over a genuinely long horizon. Acquired in 2005 as a 300-acre estate, it's been built over two decades into a working farm, a holiday-let business and an events venue – the kind of layered, multi-generational value creation that a fund's fixed term could never accommodate, and that only comes from treating the asset as a long-term project rather than a static holding.
Most family offices don't carry deep in-house real estate expertise alongside their wider investment team, which is why property is often the asset class most commonly brought in through a specialist partner rather than managed entirely in-house. Maritime Capital works alongside family offices and their existing advisers – wealth managers, investment managers and private banks – on the UK commercial property portion of the portfolio specifically, from acquisition through to ongoing asset and property management.